For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
Top Stories
UAE Employment Law: Understanding The Rules Governing 30, 60 And 90-Day Notice Periods
Employees and employers must comply with specific notice requirements under UAE Labour Law.
Resigning from a job to take up a new opportunity involves more than submitting a resignation letter. Employees in the UAE must also consider the notice period stipulated in their employment contracts, as failure to comply with these requirements can result in financial consequences.
Under UAE Labour Law, private-sector employment contracts generally carry notice periods ranging from 30 to 90 days. The applicable period depends on the contractual terms agreed between the employer and employee. The law also provides specific provisions covering early release, compensation for unserved notice and employees who are still under probation.
Understanding these requirements can help employees plan their departure without jeopardising their legal and financial entitlements. Here is what the law provides.
What Does a Notice Period Mean?
A notice period is the period an employee or employer must give before bringing an employment relationship to an end. It provides both parties with time to make the necessary arrangements, whether that involves finding a replacement, transferring responsibilities or securing alternative employment.
The obligation applies to both employees who resign and employers who decide to terminate an employment contract. The applicable notice period is generally determined by the terms specified in the employment contract.
How Many Days' Notice Must You Give?
Article 43 of Federal Decree-Law No. 33 of 2021 on the Regulation of Labour Relations establishes the notice period requirements for private-sector employment.
Under this provision, the notice period must be:
- 30 calendar days: The minimum statutory notice period.
- 90 calendar days: The maximum statutory notice period.
An employment contract may specify any period within this range, depending on the agreement between the parties.
The same notice period must generally apply to both the employer and employee. However, a different arrangement may be agreed upon where it is more beneficial to the employee.
Must Employees Continue Working Throughout the Notice Period?
As a general rule, yes. The employment contract remains in force throughout the notice period, and employees are expected to continue performing their duties unless the employer agrees otherwise.
During this period, employees are entitled to receive their full wage calculated on the basis of their last wage.
However, an employer and employee may mutually agree to waive the notice period or reduce its duration. Such an agreement must not prejudice the employee's legal entitlements.
What Happens if You Leave Without Completing the Notice Period?
Failure to comply with the contractual notice requirement can result in financial liability for the party responsible.
Under Article 43, the party that fails to observe the notice period must compensate the other party through what is commonly referred to as notice period compensation or notice allowance.
The amount is equivalent to the employee's wage for the full notice period or the unserved portion, depending on the circumstances.
For example, if an employee is required to serve 60 days' notice but leaves after completing only 30 days without an agreed waiver, compensation may be payable for the remaining 30 days.
The obligation applies whether the failure to provide the required notice is by the employee or the employer.
Can Employees Take Time Off to Search for Another Job?
Employees whose contracts are terminated by their employers are entitled to one unpaid working day off each week during the notice period to look for alternative employment.
The employee may choose the day, provided the employer is informed at least three days in advance.
This entitlement is specifically available where the employer initiates the termination. It does not automatically extend to employees who voluntarily resign.
What are the Notice Requirements During Probation?
Employees serving probation are subject to different notice requirements under Article 9 of UAE Labour Law.
The applicable rules depend on whether an employee intends to move to another employer within the UAE or leave the country.
Moving to Another UAE Employer
An employee who wishes to join another employer in the UAE must give the existing employer at least one month's written notice.
In such circumstances, the new employer is required to compensate the previous employer for the recruitment or contracting costs incurred in employing the worker, unless the parties agree otherwise.
Leaving the UAE
An employee who intends to terminate their employment during probation and leave the UAE must provide at least 14 days' written notice.
However, if the employee subsequently returns to the UAE and obtains a new work permit within three months of departure, the new employer may be required to compensate the previous employer for recruitment costs, unless otherwise agreed.
What if an Employee Leaves Without Notice During Probation?
The probationary notice requirements are legally binding, and failure to comply can result in compensation.
Under Article 9, the party that does not observe the required notice period must compensate the other party for the unserved portion.
There may also be immigration and employment consequences for foreign workers who leave the UAE without complying with the applicable probation notice requirements.
In particular, a foreign worker who leaves the country in breach of these requirements may face a one-year restriction on obtaining a new UAE work permit, subject to the exemptions provided under the law.
Employees should therefore ensure that they understand their contractual obligations before resigning or accepting another employment offer.
Ford, Honda, Stellantis And Volkswagen Sue State Of New Jersey Over New Vehicle Repair Law
Automakers claim the legislation allows dealers to impose excessive charges for warranty and recall repairs.
Ford, Honda, Stellantis subsidiary FCA and Volkswagen have sued the state of New Jersey in an attempt to block a new law that they say significantly increases the amounts automakers must pay franchised dealers for warranty and recall repairs.
In a complaint filed in federal court in Trenton, New Jersey, on Friday, the automakers argued that the New Jersey Motor Vehicle Open Recall Notice and Fair Compensation Act gives dealers a “blank cheque” to set prices for warranty, recall and other repair services, while preventing manufacturers from avoiding what they describe as “extortionate” charges or recovering the additional costs.
The legislation could transfer more than $375 million annually from automakers to dealers, giving the latter a financial “windfall” without requiring them to use the additional revenue to improve customer service or increase employee compensation, the companies said.
“In short, the act rewards dealers for charging their customers more,” the automakers said in the complaint.
The office of New Jersey Attorney General Jennifer Davenport, responsible for enforcing the state's laws, declined to comment.
The legislation came into effect on April 1, following its signing by former Governor Phil Murphy in September 2025.
Constitutional Violations Alleged
The automakers challenged a provision allowing dealers to apply a “labour multiplier” based on samples of repair orders, arguing that it enables them to bill manufacturers for substantially more labour time than technicians actually spend carrying out the work.
They also objected to provisions requiring manufacturers to pay marked-up prices for parts that dealers may have obtained at discounted rates or free of charge. Another provision prevents automakers from supplying less expensive parts, even when market conditions, supply and demand or other factors justify lower prices, they said.
Ford, Honda, FCA, which includes Fiat and Chrysler, and Volkswagen said that since the law took effect, each company had received dozens of invoices demanding payment “for hours that no technician works, that surpass what comparable dealers charge for the same work, and that exceed what retail customers pay”.
The companies argued that the legislation violates the US Constitution's Commerce Clause and Takings Clause, is overridden by federal law governing vehicle recalls and also breaches the New Jersey Constitution.
The New Jersey Coalition of Automotive Retailers, a non-profit advocacy organisation, is also named as a defendant.
Its president, Laura Perrotta, said she was confident the organisation would prevail. She accused automakers of having benefited for decades from substantial discounts on parts and labour at dealers' expense.
She also argued that dealers competing for customers should not be expected to pass the costs of warranty and recall repairs on to consumers, describing such an approach as “not an option”.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
UAE Evidence Laws: How Hiding Facts And Misleading Investigators Can Become Criminal Offences
Hiding documents or misleading investigators can expose even those unconnected with the original crime to criminal prosecution.
Discovering that a friend or relative has been involved in a criminal incident can place someone in a difficult position. You may have witnessed part of the incident, received a message that could help establish what happened or been asked to keep a particular document out of sight. While you may have played no part in the original offence, deliberately withholding or concealing information to frustrate an investigation could expose you to criminal liability.
Many people assume that criminal responsibility rests solely with the person who committed the underlying offence. UAE law, however, recognises that interference with the process of uncovering the truth can constitute a separate criminal act, even where the individual concerned had no involvement in the original incident.
Evidence plays a fundamental role in establishing the facts, identifying those responsible and enabling judicial authorities to determine criminal liability. Destroying records, hiding relevant material or knowingly giving investigators misleading information can consequently have serious legal implications. An attempt to protect another person may create a separate legal problem for the individual providing that protection.
When Interference With an Investigation Becomes an Offence
Federal Decree-Law No. 31 of 2021 on the Crimes and Penalties Law contains provisions addressing attempts to obstruct investigations and interfere with judicial proceedings.
Article 315 deals with conduct intended to mislead judicial or investigation authorities, including those responsible for gathering evidence. It provides for incarceration where a person deliberately alters circumstances relating to individuals, places or objects, conceals evidence of a crime or knowingly provides false information with the intention of misleading the competent authorities.
The provision is not confined to physically removing or destroying evidence. Manipulating the circumstances surrounding an incident or deliberately giving investigators an inaccurate account may also bring a person's conduct under scrutiny.
Consider someone who witnesses an assault and subsequently removes objects from the scene to create a false impression of what happened. Although that individual may not have participated in the assault, deliberately changing the circumstances to mislead investigators could give rise to criminal liability under Article 315, provided the necessary legal elements are established.
The distinction is important. Remaining silent and actively interfering with an investigation are not necessarily the same thing. The intention behind the conduct, particularly whether it was designed to mislead the authorities, is central to determining whether the provision applies.
Hiding or Destroying Documents Can Attract Separate Penalties
Article 316 addresses the concealment, destruction or appropriation of documents, deeds and other items connected with an investigation or judicial proceedings, where the conduct is intended to mislead the judiciary or investigation authorities. The provision prescribes incarceration and a fine.
Its scope also extends to circumstances in which relevant material has not yet been physically handed over to the authorities. It covers situations where a document or item remains with the person who originally submitted it, pending a request for its production.
This has particular significance for businesses and individuals who hold records that could become relevant to an investigation or court proceedings. Retaining possession of a document does not necessarily place someone beyond the reach of the law if it is deliberately concealed or destroyed for an unlawful purpose.
For example, a company may become the subject of a commercial investigation involving financial transactions. If an employee deliberately destroys or hides accounting records to prevent investigators from establishing the nature of those transactions, Article 316 may become relevant.
The legal concern extends beyond the disappearance of the material itself. What matters is whether someone deliberately interfered with documents or other items connected with judicial or investigative proceedings to compromise the authorities' ability to establish the facts.
The Legal Obligation to Produce Evidence
A separate issue arises when a person fails to produce material that could assist a court in establishing a fact. Article 317 addresses situations in which an individual is legally required to produce a document or another object but fails to comply.
The provision prescribes incarceration for a period not exceeding six months or a fine not exceeding Dh5,000, except where the failure to produce the material is permitted by law.
There is an important distinction between this provision and the preceding articles. Article 317 does not create a general obligation for everyone to volunteer documents or disclose every piece of information in their possession. It concerns a failure to comply with an existing legal obligation to produce relevant material, subject to the exceptions recognised by law.
This distinction is significant because the administration of justice must operate alongside the legal rights of individuals. A person who does not voluntarily disclose information cannot automatically be treated in the same way as someone who disregards a legally enforceable requirement to produce evidence.
Digital Records Present New Challenges
The growing reliance on electronic communications and digital platforms has changed the nature of evidence in criminal investigations. Messages exchanged through applications, emails, CCTV recordings, electronic transaction histories and other digital records can all help investigators reconstruct events and establish the sequence of transactions or communications.
Deleting messages after learning that they may be examined as part of an investigation, or removing CCTV footage to prevent authorities from determining what happened at a particular location, could raise questions about deliberate interference with evidence.
Nevertheless, deleting electronic information does not automatically amount to a criminal offence. Investigators and courts must consider the circumstances surrounding its removal, the individual's knowledge, the purpose of the action and whether the relevant statutory requirements have been satisfied.
Where the necessary elements are established, the deliberate concealment or destruction of electronic material may raise issues under the provisions dealing with interference with evidence. Information does not become legally insignificant simply because it is stored on a mobile telephone, computer or online platform rather than in a physical document.
For individuals and companies, the practical lesson is that electronic records deserve the same attention as paper documents. Once an investigation or legal dispute is anticipated, potentially relevant digital information should be preserved rather than deleted, altered or otherwise compromised.
Can Loyalty to a Friend or Relative Provide a Defence?
Some of the more complicated situations arise when individuals conceal information to protect someone close to them. A family member may hide an object to shield a relative, an employee may remove company records following instructions from a senior colleague, or a friend may give investigators an inaccurate account in the hope of helping an accused person avoid prosecution.
Although the motivations may differ, personal loyalty, fear or pressure does not automatically eliminate the possibility of criminal liability.
The Crimes and Penalties Law also contains provisions dealing with assistance given to offenders. Article 337, for instance, addresses knowingly helping an offender evade justice through conduct that includes concealing evidence, providing false information or otherwise assisting the person, subject to the circumstances and penalties prescribed by law.
However, the existence of a personal relationship with an accused individual does not, by itself, establish criminal responsibility. Nor does simply knowing that an offence has occurred or choosing not to volunteer information automatically amount to an offence.
The authorities must examine the individual's actual conduct, knowledge and intention, together with the statutory requirements and any applicable exceptions. The legal position depends on what the person did and the circumstances in which the assistance was provided, rather than merely their relationship with the accused.
Why Intention and Circumstances Matter
A critical factor in assessing liability under these provisions is the difference between deliberate interference with evidence and an innocent failure to preserve or produce information.
A document may be misplaced during routine business operations. CCTV footage may be deleted accidentally, or an individual may be unable to produce a particular item because it is no longer in their possession. Such situations cannot automatically be equated with deliberately destroying or concealing evidence to mislead investigators.
Articles 315 and 316 specifically address conduct involving an intention or purpose to mislead the relevant authorities. Article 317, meanwhile, concerns non-compliance with a legal obligation to produce material that may help establish a fact before a court, subject to the statutory exceptions.
Consequently, the mere fact that evidence is unavailable does not establish that a criminal offence has occurred. The nature of the conduct, the circumstances surrounding it and the applicable legal requirements must all be examined before responsibility can be determined.
This distinction is an important safeguard against treating genuine mistakes, accidental loss or an inability to produce information as deliberate attempts to obstruct justice.
Preserving Evidence is Part of Legal Compliance
The UAE's approach to evidence concealment reflects a fundamental principle of criminal justice: accountability depends not only on identifying those who commit offences but also on protecting the integrity of the investigations and judicial proceedings through which responsibility is established.
Individuals should avoid destroying, altering, hiding or manipulating material that could be relevant to an investigation, whether their intention is to protect themselves or someone else. Where a competent authority requests documents or information, it is equally important to understand the nature of the legal obligation and seek appropriate legal advice before taking action.
Businesses have comparable responsibilities. Maintaining accurate records, implementing effective document-retention policies and ensuring that potentially relevant electronic information is preserved when disputes or investigations arise can help minimise legal exposure. Employees should also exercise caution when instructed to remove, modify or dispose of records that may have evidential significance.
Conclusion
Silence alone does not necessarily constitute a criminal offence under UAE law. Equally, every failure to disclose information or produce a document does not automatically result in criminal liability. The legal position changes when a person deliberately conceals, destroys or manipulates evidence with the intention of misleading investigators or interfering with judicial proceedings.
Such conduct can expose an individual to a separate criminal investigation, even if that person had no involvement in the original offence. The consequences may extend far beyond the incident they initially sought to keep hidden.
Protecting someone from accountability can itself become a criminal matter. In the UAE, an attempt to conceal the truth may ultimately place the person responsible for hiding it under investigation.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
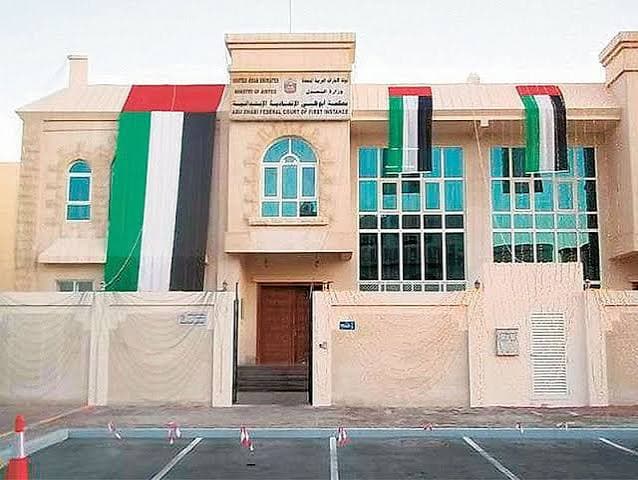
Abu Dhabi Commercial Court Orders Marine Services Company To Pay $49,359 In Unpaid Dues
Court rejects late-delivery cancellation defence, ruling that the buyer failed to follow contractual notice requirements.
The Abu Dhabi Commercial Court of First Instance has ordered the Abu Dhabi branch of a foreign marine services company to pay $49,359.60 to a marine supplier, rejecting the buyer's attempt to avoid part of the outstanding debt by invoking a contractual clause allowing cancellation for late delivery.
In a judgment dated November 11, 2026, the court ordered payment of the full claimed amount, or its equivalent in UAE dirhams at the date of payment, together with annual interest of 3% from the date the claim was filed until settlement, subject to a cap of the principal amount. The buyer was also ordered to pay court costs.
The dispute arose from six purchase orders issued between February and March 2024 for marine supplies intended for a vessel. The orders covered batteries, lubricants, paints, silica gel, grease and insulated ladders, with delivery scheduled in Pointe Noire, Congo. Payment was due within 30 days of invoicing.
The supplier delivered the goods, and the buyer's representatives signed and stamped the delivery documents. However, payment remained outstanding. A statement of account issued in April 2025 showed an unpaid balance of $49,359.60, prompting the supplier to initiate legal proceedings on October 28, 2026.
The buyer acknowledged the commercial relationship and deliveries but disputed part of the claim. It accepted that approximately $8,444 relating to three invoices remained unpaid, while arguing that late delivery under two other purchase orders entitled it to cancel those orders and avoid the corresponding payments.
The court examined the purchase orders, tax invoices, signed delivery notes, email correspondence and statement of account. It accepted the documentary evidence, relying on Article 34 of the Commercial Transactions Law and relevant Abu Dhabi Court of Cassation principles concerning commercial records and electronic evidence.
The court held that properly maintained electronic accounting records could carry the same evidential weight as regular commercial books. Such records would bind the opposing merchant unless rebutted through its own regular books or other admissible evidence. The buyer had failed to provide such a rebuttal. The court also recognised the evidential value of electronic correspondence and treated admissions in the buyer's written response as binding judicial admissions.
A decisive issue was whether the buyer had exercised its contractual cancellation rights in accordance with the agreed purchase terms. The contract provided for liquidated damages of 1% of the order value for each full week of delay, subject to a maximum of 10%. It also allowed termination without liability if delivery was delayed by more than five weeks. A separate provision permitted cancellation if the supplier failed to remedy a breach within seven days of receiving notice.
The court found that the buyer had not established a valid basis for cancellation under either provision. In relation to the first disputed order, the delay had not exceeded five weeks. In the second instance, although the delay exceeded that period, the buyer had failed to issue notice within the contractual timeframe.
The supplier had informed the buyer by email on April 18, 2024, apologising for the delay and promising delivery the following day. The buyer subsequently confirmed shipment by sea to Abu Dhabi on April 25, received the goods on April 26, and issued its cancellation notice only on April 27. The court found that the cancellation had not been exercised in accordance with the contractual requirements.
It concluded that the buyer could not rely on the cancellation provisions to avoid payment. Its remedy was limited to claiming the agreed liquidated damages, provided these were properly claimed and established. As no such claim had been proved, the defence was rejected.
The court awarded interest at 3% annually from October 28, 2026, the date of filing, until full payment, subject to the principal amount. It declined the supplier's request for 5% interest calculated from April 28, 2024, finding that the parties had not agreed on an interest rate. The contractual 30-day payment period established the due date but did not, by itself, determine the applicable interest rate.
The litigation was led by UAE-based legal consultancy Kaden Boriss, represented by its local counsel Ayesha Al Zaabi, which pursued recovery of the outstanding amount through documentary evidence and contractual interpretation.
The judgment highlights the importance of maintaining proper commercial records, including purchase orders, invoices, delivery confirmations and statements of account. It also reinforces the principle that contractual cancellation rights must be exercised strictly in accordance with agreed notice periods and conditions.
Abu Dhabi court awards $49,359.60 to a marine supplier after rejecting a buyer's late-delivery cancellation defence over unpaid vessel supplies and invoices.
For businesses engaged in cross-border commercial transactions, the ruling underlines the value of clear contractual provisions, documented communications and timely enforcement of payment obligations. It also demonstrates how a party's own correspondence and subsequent conduct may become significant evidence when the validity of a contractual defence is examined.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
The Money Mule Trap: How UAE Bank Account Holders Can Become Entangled in Financial Crime
UAE money mules face imprisonment and heavy fines for handling illicit funds through personal and corporate accounts.
An invitation to receive money into a bank account and transfer it elsewhere may sound like an easy way to earn additional income. It could be presented as a part-time job, an administrative task or a service for which the account holder receives a commission. In reality, such arrangements can form part of a money laundering operation, placing individuals who agree to participate at risk of criminal investigation in the UAE.
A person who allows their bank account to be used to receive and move funds on behalf of others is commonly described as a money mule. Criminal networks use these intermediaries to distance themselves from the proceeds of fraud and other offences. By moving money through several accounts, they attempt to disguise its origin and make it harder for banks and investigators to identify the ultimate beneficiaries.
The methods vary. Some individuals are asked to rent out their accounts or hand over banking credentials, while others receive transfers from unfamiliar people and forward the money to designated beneficiaries. More elaborate arrangements involve setting up companies, issuing invoices for services never provided or converting cryptocurrency into cash.
Although some participants knowingly assist criminal networks, others may be drawn in through misleading employment advertisements, social media approaches or promises of legitimate commissions. Their knowledge and conduct, however, remain central to determining whether criminal liability arises.
How Money Mule Arrangements Operate
Money mule schemes rely on the use of accounts belonging to people who are not directly involved in the original criminal activity. Funds obtained through fraud or other unlawful conduct may first enter a personal account before being transferred to several other accounts. Each additional transaction can make the movement of the money more difficult to trace.
Recruitment often takes place online. An individual may be told that a company needs someone to receive customer payments, process transactions or manage transfers because of restrictions on its own banking arrangements. The person is promised a fixed payment or a percentage of the money handled.
Other schemes involve opening bank accounts or registering companies for third parties. Participants may be instructed to share debit cards, passwords or one-time passwords, or to use their accounts to receive payments from people they have never dealt with.
The use of corporate accounts can make these arrangements appear more credible. Payments may be described as consultancy fees, marketing expenses or purchases of equipment, even where no goods have been delivered or services performed. Such transactions can create a false appearance of ordinary business activity.
An account holder who accepts these instructions may become involved in the movement of criminal proceeds, even if they did not participate in the offence that generated the money.
The UAE's Legal Framework
The principal legislation governing money laundering in the UAE is Federal Decree-Law No. 10 of 2025 Regarding Anti-Money Laundering, and Combating the Financing of Terrorism and Proliferation Financing. The law replaced Federal Decree-Law No. 20 of 2018 and came into force on October 14, 2025.
Article 2 defines the conduct that may constitute money laundering. It applies where a person knows, or where sufficient indications or evidence exist to believe, that funds represent proceeds of a predicate offence and intentionally converts, transfers or carries out transactions involving those proceeds for the purpose of concealing or disguising their illicit origin.
The provision also covers concealing the true nature, source, location, movement or ownership of criminal proceeds, as well as acquiring, possessing or using them. Assisting the perpetrator of the underlying offence to evade punishment is also included.
Money laundering is treated as a separate criminal offence. A conviction for the original crime is not necessary to establish the illegal origin of the proceeds. Knowledge may be inferred from the circumstances surrounding the transactions, rather than being determined solely by what an individual claims to have known.
This distinction is important in money mule cases. Someone who did not organise a fraud may still face investigation for handling or transferring its proceeds. However, the mere receipt of suspicious funds does not automatically establish money laundering. The relevant statutory requirements, including knowledge and intentional conduct, must be assessed against the available evidence.
The Criminal Consequences
The penalties under the 2025 law are significant. Article 26 provides for imprisonment of between one and ten years and a fine of Dh100,000 to Dh5 million, or an amount equivalent to the value of the criminal property, whichever is greater.
The legislation also prescribes enhanced punishment where specified aggravated circumstances are established. These include exploiting influence or authority arising from a person's position or professional activity, committing the offence through a non-profit organisation or an organised criminal group, certain specified predicate offences and repeat offending. The penalty is temporary imprisonment and a fine of between Dh1 million and Dh10 million, or twice the value of the relevant criminal property, whichever is greater.
The consequences may extend beyond imprisonment and fines. Competent authorities may take measures to identify, seize or freeze suspected criminal assets, while confiscation may be ordered in accordance with the law.
For someone who agreed to process payments in return for a relatively small commission, the financial and criminal consequences can be disproportionate to the amount received.
When Cybercrime Offences are Also Involved
Money mule operations frequently rely on digital platforms and electronic transactions. Criminal networks may use false identities, fabricated company profiles, forged documents and payment instruments to facilitate the movement of funds.
Federal Decree-Law No. 34 of 2021 on Countering Rumours and Cybercrimes contains provisions that may apply to aspects of these activities. Article 11 addresses the creation of fake websites, electronic accounts and email addresses falsely attributed to another natural or legal person.
Article 14 deals with the forgery of electronic documents and the knowing use of forged documents. Article 15 covers the forgery, cloning or copying of credit cards, debit cards and other electronic payment instruments, as well as the capture of their data or information.
These provisions may become relevant where criminal networks impersonate individuals or companies, create fictitious online business profiles, use forged electronic invoices or forge payment instruments. Depending on the conduct and the evidence, a scheme may give rise to investigations involving both money laundering and cybercrime offences.
When an Individual Claims to Have Been Deceived
One of the important questions in a money mule investigation is whether the account holder knew, or had sufficient indications or evidence to believe, that the funds were connected to criminal activity.
Consider an individual who responds to an online advertisement for a remote administrative position. The supposed employer explains that the job involves receiving customer payments into a personal bank account and transferring them to other accounts. In return, the individual is offered a monthly salary and an additional commission for each transaction.
The arrangement may initially appear genuine. However, the person is subsequently instructed to accept transfers from unrelated individuals, forward the money immediately, retain a percentage and avoid contacting the senders. If the funds are later traced to fraudulent activity, the account holder's role may come under scrutiny.
Investigators may examine the nature of the employment offer, the value and frequency of transfers, the commission received and communications with the supposed employer. Instructions to conceal transactions from the bank, share banking credentials or provide misleading explanations may also be relevant.
A person who has genuinely been deceived should not automatically be treated as a money launderer. Equally, a claim that the account holder did not know where the money came from will not, by itself, resolve the matter. The individual's conduct and the surrounding evidence will be important in determining whether the legal requirements for an offence have been satisfied.
The Risks of Using Companies and False Invoices
Criminal networks may use registered businesses to give illicit funds the appearance of legitimate commercial income. Corporate accounts can be used to receive payments supported by invoices for consultancy, marketing, equipment or other services that were never supplied.
Once the money enters the business account, it may be transferred to other entities, withdrawn or converted into virtual assets. The use of commercial documents can make the transactions appear routine, even when there is no genuine business purpose behind them.
Company registration and possession of a trade licence do not legitimise criminal proceeds. Directors, managers and business owners should ensure that payments correspond to actual supplies or services and that invoices are supported by appropriate contracts and records.
Unexplained transfers from unrelated third parties, unusually high commissions and requests to process payments outside the company's normal activities should be examined carefully. Businesses should also be alert to attempts to use their accounts as a channel for funds unrelated to their operations.
Steps to Protect Personal and Corporate Accounts
Individuals should not rent out their bank accounts, hand over debit cards or share passwords, PINs, one-time passwords or online banking access with third parties. Offers of employment that require a person to receive money into a personal account and transfer it elsewhere should be treated with particular caution.
Anyone approached with such a request should retain relevant messages, emails and other communications. If suspicious funds have already been received or transferred, the individual should contact the bank through its official channels and obtain appropriate legal advice. Further transfers should be avoided, and relevant records should not be deleted or altered.
Businesses need controls that verify customers, suppliers and other counterparties, establish the commercial purpose of payments and restrict access to corporate banking facilities. Accounting records, contracts and invoices should accurately reflect genuine transactions. Unexplained payments should be referred to the appropriate compliance personnel.
Financial institutions, designated non-financial businesses and professions (DNFBPs), virtual asset service providers and other regulated entities may also be subject to obligations under the UAE's anti-money laundering framework. These can include customer due diligence, transaction monitoring, record-keeping and suspicious transaction reporting.
The Role of Investigations and International Cooperation
Suspicious financial activity can trigger reporting and other measures under the applicable legal framework. Depending on the circumstances and legal authority, transactions may be suspended and funds frozen while competent authorities examine the activity.
Investigations may follow the movement of money across multiple bank accounts, companies and digital wallets. Banking records, electronic communications, transaction histories and commercial documents can help establish who controlled the funds, how they were transferred and whether the accounts were used to conceal criminal proceeds.
Cross-border cooperation is also important. Funds may pass through several jurisdictions before reaching their intended beneficiaries, making it necessary for UAE authorities to work with foreign counterparts and financial institutions to trace transactions and identify those involved.
Conclusion: The Cost of Handling Money for Others
Money mule arrangements demonstrate how easily personal bank accounts, corporate banking facilities and digital wallets can be exploited by criminal networks. What appears to be a convenient source of additional income may expose an individual to investigation, imprisonment and substantial financial penalties.
The UAE's anti-money laundering and cybercrime laws provide a framework for investigating the movement and concealment of criminal proceeds. At the same time, genuine victims of deception must be distinguished from individuals who knowingly participate in such arrangements. The circumstances of each case, particularly what the account holder knew and how they acted, remain critical.
For residents and businesses, the safest course is to reject unexplained payment requests, protect banking credentials and ensure that every transaction has a genuine and verifiable purpose. Allowing another person to use an account is not simply a banking decision; depending on the circumstances, it can carry serious legal consequences.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
Litigation Funding Turns Towards Social Media Addiction Claims Against Technology Giants
Meta, TikTok and YouTube face growing scrutiny as litigation funders back claims over alleged harm to young users.
Litigation funders are showing increasing interest in lawsuits accusing major social media companies of designing platforms that encourage addictive behaviour among young users, adding a new financial dimension to a growing wave of legal action against the technology industry in the United States.
Houston-based Armadillo Litigation Funding is backing The Law Office of Paul Mankin in cases against social media platforms, according to court filings reported by Bloomberg Law on November 18.
The filings identify Armadillo as an interested party in five cases forming part of the multidistrict litigation over Social Media Adolescent Addiction in the Northern District of California. The proceedings involve claims against Meta Platforms, TikTok and Google's YouTube.
The lawsuits allege that the platforms were designed to encourage excessive use and that their features contributed to personal injuries among young users, including depression, anxiety, eating disorders and self-harm. The allegations remain subject to judicial determination.
The involvement of litigation funders highlights the growing commercial interest in claims against technology companies, particularly as plaintiffs pursue legal arguments concerning platform design, user engagement and the protection of children online.
Funding Adds a New Dimension to Mass Litigation
Litigation funding allows specialist finance providers to support legal proceedings by covering costs such as legal fees, expert evidence and case development. In return, funders generally receive an agreed share of any financial recovery, subject to the terms of the funding arrangement.
For claims involving large technology companies, external financing can help plaintiffs and law firms sustain proceedings that may require substantial resources and extend over several years.
The social media addiction litigation presents a potentially significant opportunity for the funding industry. However, the claims also involve legal and evidential uncertainties, particularly in establishing the connection between platform design, individual use patterns and alleged psychological harm.
Platform Design at the Centre of the Dispute
The litigation centres on whether social media companies can be held liable for the design and operation of their platforms, rather than simply for content posted by third parties.
That distinction has important legal implications in the United States, where technology companies have frequently relied on Section 230 of the Communications Decency Act to defend themselves against claims arising from user-generated content.
Plaintiffs in the social media cases have sought to distinguish product-design and negligence claims from claims based solely on the publication of third-party content. The distinction could influence how courts assess the extent of platform operators' responsibilities towards younger users.
The proceedings also raise wider questions about the responsibilities of technology companies in developing recommendation systems, engagement features and safeguards for minors.
A Developing Test for Technology Companies
The growing interest from litigation funders comes as social media addiction claims move through different stages of litigation in the United States. The outcome of these proceedings could influence the approach taken by plaintiffs, defendants and investors considering similar claims.
For technology companies, the litigation presents risks extending beyond potential damages. Court scrutiny of platform design, internal decision-making and child-safety measures could also affect compliance practices and product development.
For litigation funders, the cases offer the possibility of substantial returns but carry considerable uncertainty over liability, causation, litigation duration and the prospects of recovery.
As the proceedings develop, the interaction between litigation finance and claims involving digital platforms is likely to attract greater attention from the legal and investment sectors.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
Ajman Court Of Appeal Orders Joint Recovery Of Dh735,188 In Commercial Financial Dispute
Court overturns lower court ruling, ordering repayment of Dh735,188 after expert findings support the financial claim.
The Ajman Federal Court of Appeal has overturned a Court of First Instance judgment and ordered two respondents to jointly pay Dh735,188.32 in a commercial financial dispute, together with 5% legal interest until full payment, legal fees and litigation expenses.
The dispute arose from a commercial arrangement under which an individual advanced funds to finance purchase orders and facilitate services for hotels and other companies. Despite an agreement to repay the money within the stipulated period, the amount remained outstanding, raising questions over the authenticity of the supporting purchase orders and the use of the funds. The failure to recover the money resulted in a substantial financial claim and subsequent legal proceedings.
The claimant initiated civil proceedings seeking recovery of the outstanding amount. However, the Court of First Instance dismissed the claim on the grounds that it was premature. The decision was subsequently challenged before the Ajman Federal Court of Appeal, where the appeal focused on establishing the financial transactions, the nature of the funds advanced and the respondents' liability for repayment.
A central element of the appeal was an independent accounting expert's examination of the financial records and supporting documents. The expert confirmed that Dh630,866 had been transferred to the company's bank account and identified signed acknowledgments corresponding to the claimed amount of Dh735,188.32. The examination also found that the purchase orders under review did not belong to the entities to which they had been attributed.
The bank transfer records, written acknowledgments and expert findings were presented before the Court of Appeal to establish the movement of funds and substantiate the repayment claim. The evidence also addressed the distinction between the personal funds advanced and any amounts associated with the company's share capital.
In its judgment dated September 29, 2026, the Ajman Federal Court of Appeal accepted the appeal, overturned the lower court's decision and ruled in favour of the claimant. It ordered the respondents to jointly pay Dh735,188.32, together with 5% legal interest calculated from the date of filing the claim until full payment.
The court also awarded Dh10,000 in legal fees covering both levels of litigation and ordered payment of the applicable court expenses. It further recognised that the amount claimed represented personal funds advanced for the commercial arrangement rather than a contribution to the company's share capital.
The litigation was led by UAE-based legal consultancy Kaden Boriss, represented by its local counsel Ayesha Al Zaabi. The legal proceedings focused on establishing the financial liability through documentary evidence, transaction records and independent expert assessment.
The judgment highlights the importance of maintaining reliable financial records and obtaining independent expert assessments in commercial disputes involving advances, purchase orders and repayment obligations. It also demonstrates the role of appellate proceedings in reconsidering claims where documentary and expert evidence may establish financial liability that was not recognised at the first-instance stage.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
UAE Foundations: Legal Frameworks For Preserving Family Wealth And Managing Succession
DIFC, ADGM & RAK ICC foundations can support asset ownership, intergenerational wealth transfer & tax planning under UAE.
Foundations have become an important option for families and investors seeking a structured approach to managing wealth, holding assets and planning for succession in the UAE. Established as independent legal entities, they can own property, investments and other assets while operating under a set of rules governing their administration and distribution. The DIFC, ADGM and RAK ICC each offer a legislative framework for setting up such structures. Their use, however, requires careful consideration of the legal consequences of transferring ownership, the powers retained by founders, the protection available against creditor claims and the tax treatment that may apply. The choice of jurisdiction and the design of the foundation must be aligned with the founder's long-term objectives.
Understanding the UAE's Foundation Regimes
The legal basis for establishing foundations in the UAE is provided by the DIFC Foundations Law (DIFC Law No. 3 of 2018), the ADGM Foundations Regulations 2017 and the RAK ICC Foundations Regulations 2019, as amended. Under each framework, a foundation has a legal identity distinct from its founder and beneficiaries. The DIFC and RAK ICC legislation further establishes that foundation property is not held on trust for another person. The founder's rights are determined by the provisions of the charter and by-laws rather than by any automatic entitlement to the foundation's assets.
The ADGM framework describes a foundation as an entity possessing certain characteristics of a company but without shareholders. It may be established for charitable or non-charitable purposes, or to benefit individuals identified by name or through membership of a particular category or class. Its role is not that of a conventional trading enterprise. The DIFC and RAK ICC regimes similarly restrict commercial activities, allowing them only where they are necessary for, or ancillary or incidental to, the foundation's stated objectives.
These restrictions have implications beyond the legal form of the entity, particularly when assessing its activities for Corporate Tax purposes. There are also practical differences between the three jurisdictions concerning registered agents, minimum capital requirements and the courts with supervisory authority. A founder should consider the nature of the proposed assets, the intended beneficiaries and the expected duration of the arrangement before deciding which framework is most appropriate.
Transferring and Holding Family Assets
The legislation permits foundations to hold a wide range of property. Under the DIFC and RAK ICC frameworks, this includes movable and immovable assets as well as rights and interests connected with them. Company shares, financial investments, interests in real estate and intellectual property may therefore be transferred into a foundation, subject to the applicable legal requirements.
The foundation's capacity to own property does not remove the need to comply with the laws governing individual assets. Where immovable property is situated outside the DIFC, for example, its transfer must satisfy the requirements of the jurisdiction in which it is located. A foundation cannot acquire a valid title through legislation that does not govern the underlying property. Equally, a transfer cannot be effective where the founder lacked legal ownership or the authority to dispose of the asset.
The rights of beneficiaries are also defined by the foundation's governing documents. Under the relevant regimes, beneficiaries, known as qualified recipients, are entitled to receive distributions in accordance with the by-laws. This entitlement does not ordinarily amount to ownership of the foundation's property. Instead, it represents a right to receive the benefits specified in the governing documents. The distinction allows the foundation to retain ownership while providing for the financial interests of designated family members or other recipients.
Succession Planning and Protection Against Claims
The DIFC and RAK ICC frameworks contain provisions intended to address the effect of foreign inheritance rules on foundation property. Heirship rights arising under foreign law in respect of the property of a living person are not recognised as affecting ownership of immovable property within the relevant jurisdiction or movable property wherever situated.
This can be relevant to families with international connections, particularly where their assets, beneficiaries and personal circumstances involve more than one legal system. Nevertheless, a foundation should not be treated as a means of avoiding legitimate creditor claims.
Under both regimes, a transfer to a foundation does not become invalid merely because the founder subsequently enters bankruptcy or a creditor brings proceedings. The legislation provides an exception where the transfer was made with the intention of defrauding a creditor and caused the founder to become insolvent. In such circumstances, the foundation may be required to meet the creditor's claim, limited to the founder's interest in the property transferred.
There is also a statutory time limit for challenging the arrangement. Proceedings seeking to set aside the establishment of a foundation or a disposition of property to it must be commenced within three years. The circumstances surrounding the transfer, including its timing and purpose, therefore remain important when assessing the legal protection offered by the structure. Proper planning should take place before financial difficulties or creditor disputes arise.
Managing the Foundation and Retaining Control
A foundation's administration is governed by its charter and by-laws. The council is responsible for managing the property and ensuring that the foundation pursues its stated objectives. It must have at least two members, although the founder is permitted to serve on the council. Members are expected to act honestly and in good faith and to exercise the degree of care and skill that would be expected of a reasonably prudent person. The governing documents cannot exempt council members from liability for fraud, wilful misconduct or gross negligence.
A guardian provides oversight of the council and its administration. Under the DIFC and RAK ICC regimes, a guardian must be appointed where the foundation is established for charitable purposes or a specified non-charitable object. The guardian cannot also hold membership of the council. ADGM adopts a different arrangement: the founder may choose whether to appoint a guardian during their lifetime, but the appointment becomes compulsory following the founder's death.
The founder's ability to retain decision-making powers is another significant feature of these structures. Under the DIFC and RAK ICC frameworks, the founder may reserve powers to amend or revoke the charter or by-laws, change the foundation's objects or terminate the foundation. Such powers must be expressly and fully recorded in the charter. They cease upon the founder's death or, where the founder is a corporate entity, after 50 years.
RAK ICC allows founders to reserve additional powers, including the authority to direct investments and appoint or remove council members and guardians. These provisions can offer greater flexibility where the founder wishes to maintain a degree of influence over investment decisions and administration without retaining direct ownership of the assets.
The by-laws are particularly important when the foundation is intended to continue beyond the founder's lifetime. They should establish clear rules for distributing income or capital, determining who qualifies as a beneficiary and setting out the procedures for appointing council members. The court also has the power to order amendments to the charter or by-laws where changes would assist the foundation in managing its property or fulfilling its objectives.
Corporate Tax Implications and Regulatory Compliance
The establishment of a foundation under UAE law does not automatically confer a particular tax status. Where it has separate legal personality, it generally falls within the scope of the UAE Corporate Tax regime as an independent taxable entity.
Article 17 of Federal Decree-Law No. 47 of 2022 provides a mechanism through which a Family Foundation may seek treatment as an Unincorporated Partnership by applying to the Federal Tax Authority (FTA). This is subject to specific eligibility requirements and should not be confused with an automatic exemption from Corporate Tax.
The foundation must be established for the benefit of identified or identifiable natural persons or a public benefit entity. Its principal activity should involve receiving, holding, investing, distributing or otherwise managing assets or funds associated with savings or investment. It must not carry out an activity that would constitute a Business or Business Activity if undertaken directly by its founder, settlor or a beneficiary, or if the assets were held by them personally. In addition, avoiding Corporate Tax must not be the foundation's main or principal purpose.
The Minister may prescribe further conditions, while Ministerial Decision No. 261 of 2024 provides additional requirements. Compliance with the eligibility criteria alone is insufficient. An application must be submitted to the FTA and approval obtained. Where the application succeeds, the treatment may take effect from the beginning of the Tax Period in which it was filed, a subsequent Tax Period or another date determined by the Authority. The FTA may also request information to verify that the foundation continues to meet the relevant conditions.
In June 2026, the FTA published an updated Corporate Tax Guide on the Taxation of Family Foundations (CTGFF1), superseding the edition issued in May 2025. The revised guidance deals with issues including the transfer of assets into foundations and the use of multi-tier holding arrangements. This makes it important to examine the tax consequences of the proposed structure before assets are transferred, particularly where the foundation will hold interests in other entities.
Foundations must also comply with regulatory obligations beyond Corporate Tax. Under the DIFC Operating Law, a DIFC foundation is treated as a Registered Person and must provide the Registrar with details of its ultimate beneficial owners and nominee directors in accordance with the applicable Regulations. The DIFC, ADGM and RAK ICC frameworks also impose separate requirements for maintaining accounting records.
Building a Sustainable Succession Structure
A UAE foundation can provide families with a legal mechanism to separate asset ownership from the distribution of economic benefits and to establish rules for managing wealth over successive generations. Its success depends on the suitability of the chosen jurisdiction, the validity of the initial asset transfers and the clarity of the governance arrangements. The founder's reserved powers and the rights of beneficiaries must be carefully documented, while the proposed tax treatment should be tested against Article 17 and the relevant FTA requirements. A review of the applicable legislation, ownership restrictions and continuing compliance obligations is essential before the structure is implemented.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
US Federal Judge Orders White House To Disclose Records In Trump’s Law Firm Crackdown Case
Court directs administration to hand over communications with targeted law firms and records of subsequent agreements.
A federal judge in Washington has ordered President Donald Trump’s administration to produce records sought by the American Bar Association (ABA) in its lawsuit alleging that the White House unlawfully targeted law firms over their previous legal work, diversity policies and political affiliations.
The ruling by US District Judge Amir Ali, directs the White House to disclose its communications with law firms targeted by Trump through executive orders, as well as correspondence with firms that subsequently reached agreements with the administration and records relating to those arrangements.
The ABA sued the administration last year, alleging that the White House had adopted an unlawful policy of retaliating against law firms and lawyers because of their speech and legal representations that the government opposed. The organisation, which represents attorneys across the United States, sought the records as evidence in support of its claims.
Ali rejected the association’s request for access to certain records for the time being, but said it could submit further arguments seeking their disclosure. The judge said he was carefully balancing the ABA’s need for evidence against the White House’s interest in protecting the confidentiality of its communications.
The White House had challenged the scope of the ABA’s demands, describing them as excessively broad and arguing that responding to the requests would disrupt the functioning of the executive branch.
Lauren Bis, a White House spokesperson, criticised the ruling in a statement on Monday, describing the judge as an “activist judge” seeking to compel the disclosure of protected internal communications. She added that the administration was confident the decision would not be the final word in the case.
Trump issued executive orders last year targeting several prominent law firms. The measures sought to revoke lawyers’ security clearances, restrict their access to federal buildings and threaten the termination of US government contracts held by their clients.
Nine major firms subsequently reached agreements with the White House to rescind or avoid such orders, pledging nearly $1 billion in pro bono legal services for causes supported by the administration.
The ABA’s lawsuit, brought by the largest attorney membership organisation in the United States, seeks a declaration that the administration’s alleged policy of targeting law firms violates the US Constitution. It also asks the court to prevent the White House and federal agencies from enforcing the policy.
In his latest ruling, Ali said draft versions of the executive orders could provide important evidence about the administration’s intentions.
“Drafts of the law firm orders will reveal how the language in those orders changed over time, which may shed light on the government’s motivation in issuing the orders and the desired effect of the orders on the law firms,” he wrote.
The White House has invoked presidential communications privilege to withhold the names of individual administration officials who possess information about the executive orders targeting law firms. Ali has yet to determine whether the administration’s claim to that privilege is valid.
Four judges struck down executive orders targeting law firms last year, ruling that the measures violated the firms’ constitutional rights to free speech and due process. The Trump administration is appealing those decisions.
The case is American Bar Association v. Executive Office of the President, US District Court for the District of Columbia, No. 1:25-cv-01888-AHA.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.
Prenuptial Agreements In The UAE: Can Couples Secure Their Financial Rights Before Marriage?
The enforceability of prenuptial agreements in the UAE depends on the applicable law and the legal status of the spouses.
Imagine a couple who signed a prenuptial agreement in the United Kingdom before getting married. Years later, they move to Dubai, acquire property and establish business interests. When their relationship breaks down, they face a question that neither may have considered when signing the document: will a UAE court recognise the financial arrangements they agreed upon before their wedding?
For many couples, discussing the possibility of divorce before marriage is uncomfortable. Yet, where both partners have accumulated assets, investments or business interests, leaving financial arrangements undefined can create considerable uncertainty. A prenuptial agreement can help establish expectations and protect individual interests, but its legal value depends on the applicable law and the way the agreement has been prepared.
In the UAE, there is no single rule that automatically validates every prenuptial agreement. The position depends on factors such as the spouses' nationality, religion, the legal framework governing their marriage, the contents of the agreement and the formalities followed when it was signed. An agreement that is legally effective in one country may not necessarily produce the same result in another.
Understanding these differences is particularly important for expatriates and international families whose personal and financial affairs extend across several jurisdictions.
Understanding the Purpose of a Prenuptial Agreement
A prenuptial agreement is a contract made before marriage in which the prospective spouses record how they intend to manage certain financial matters during their relationship and in the event of divorce or separation. It can cover assets owned before marriage, property acquired subsequently, investment portfolios, business interests, liabilities and certain financial obligations between the parties.
For entrepreneurs and business owners, such arrangements can be especially significant. They may wish to protect their shareholdings, preserve family business interests or prevent personal marital disputes from affecting commercial operations. Similarly, individuals entering a second marriage may want to clarify the position of assets intended for children from an earlier relationship.
However, a conventional prenuptial agreement is not necessarily equivalent to a marriage contract under UAE personal status legislation. The two may contain similar financial provisions, but their legal character and requirements can differ. In particular, an agreement prepared according to foreign legal conventions cannot automatically replace the conditions that must be incorporated into an authenticated marriage contract under the applicable UAE framework.
Three Legal Routes That Couples Should Understand
The UAE recognises different personal status arrangements, and the legal treatment of financial agreements varies accordingly. The distinction between civil marriages involving non-Muslims and marriages governed by Islamic personal status provisions is particularly important.
Non-Muslim Couples Under Federal Civil Personal Status Law
Federal Decree-Law No. 41 of 2022 on Civil Personal Status introduced a framework for non-Muslim couples in the UAE, subject to the separate arrangements applicable in Abu Dhabi.
Article 9 deals with financial claims following divorce. Where the spouses have not agreed on the terms or conditions governing alimony and other financial claims in their marriage contract, the court has discretion to determine the appropriate relief. Relevant considerations include the length of the marriage, the wife's age, the financial circumstances of both parties and the extent to which the husband's conduct contributed to the breakdown of the relationship.
The provision gives particular importance to financial arrangements recorded in the marriage contract. Couples who have documented their expectations may consequently be better placed to establish what they had agreed upon.
Nevertheless, this should not be taken to mean that any privately drafted prenuptial agreement will automatically be accepted by a UAE court. Its contents, legal character and compatibility with the applicable legislation remain relevant. The distinction between an agreement recognised within the statutory marriage framework and a separate private contract can become decisive when a dispute reaches court.
Abu Dhabi's Civil Marriage Framework
Abu Dhabi has established a more formal mechanism for non-Muslim couples wishing to record their financial arrangements before marriage.
Under Abu Dhabi Law No. 14 of 2021 on Civil Marriage and its Effects, eligible couples can enter into civil marriages and submit prenuptial agreements to the Abu Dhabi Judicial Department (ADJD) for authentication.
The judicial department provides an approved template to assist couples in preparing their agreements. The parties may also submit an agreement drafted according to their individual requirements, subject to the applicable translation and authentication procedures. The agreement is optional, but the availability of an established judicial process provides couples with a recognised route for formalising their financial arrangements.
This can be particularly useful for expatriates with international property holdings, investments and commercial interests. Rather than depending entirely on a privately signed document, couples can use a procedure specifically provided for civil prenuptial agreements.
The formalities should not be overlooked. The agreement must satisfy the relevant procedural requirements, including the submission of the required documents and the necessary Arabic and English versions. Couples should also obtain independent legal advice to ensure that the provisions reflect their actual circumstances.
Muslim Couples: The Importance of Marriage Contract Conditions
A different set of considerations applies to Muslim couples. Their marriages are governed by Federal Decree-Law No. 41 of 2024 on the Issuance of the Personal Status Law.
Article 33 addresses conditions incorporated into marriage contracts. It provides that spouses are generally bound by the conditions they have agreed upon, except where a condition makes something prohibited permissible or prohibits something that is otherwise permissible. Conditions that contradict the essence or requirements of the marriage contract, or are prohibited under Islamic Sharia, may be declared invalid.
The legislation also places importance on documentation. Where a condition is disputed, its inclusion in the authenticated marriage contract is particularly significant. A condition that satisfies the statutory and Sharia requirements may be enforceable, while a non-compliant provision may be rejected without necessarily invalidating the entire marriage contract.
For couples accustomed to Western-style prenuptial arrangements, this distinction deserves careful attention. A separate financial agreement prepared before marriage cannot simply be assumed to have the same effect as conditions properly incorporated into an authenticated Islamic marriage contract.
The appropriate legal structure should therefore be considered before the marriage takes place, rather than left until a disagreement emerges.
When the Agreement was Made Outside the UAE
One of the more challenging situations arises when a couple signs a prenuptial agreement overseas and subsequently moves to the UAE. This is common among expatriates who marry in their home countries before relocating to Dubai or another emirate for employment or business.
An overseas agreement does not automatically become invalid simply because the couple moves to the UAE. However, neither does its existence guarantee that every provision will be enforced by a local court. The applicable conflict-of-laws rules and the legal status of the spouses must be examined before its effect can be determined.
Federal Decree-Law No. 25 of 2025, which introduced the new Civil Transactions Law and came into force on June 1, 2026, contains provisions relevant to marriages involving foreign elements.
Article 13 provides that the law of the country where the marriage was concluded governs its personal and property-related effects, as well as divorce and judicial separation. This is an important consideration for couples whose marriage and subsequent financial arrangements have connections with more than one country.
Article 14 introduces a significant qualification. Where either spouse was a UAE national when the marriage took place, or subsequently acquired UAE nationality and retained it until the commencement of legal proceedings, UAE law applies exclusively, except in relation to the legal capacity to marry.
The new legislation also retains the importance of public policy considerations. Under Article 29, foreign law cannot be applied where its provisions conflict with UAE public order or public morals. This places a limit on the extent to which parties can rely on foreign legal provisions in proceedings before UAE courts.
For couples with overseas prenuptial agreements, the practical implication is that the document must be assessed in the context of these rules rather than treated as a universally enforceable contract. Its provisions, the law governing the marriage and any mandatory UAE legal requirements may all influence the outcome.
A further consideration is that the Civil Transactions Law is relatively new. Although its provisions establish the relevant legal framework, their application to particular prenuptial arrangements will depend on judicial interpretation and the circumstances of individual disputes. Obtaining a UAE legal review before relying on an overseas agreement is therefore advisable.
Are There Limits to What a Prenuptial Agreement Can Cover?
Although couples have considerable scope to establish their financial expectations, a prenuptial agreement cannot override every legal obligation arising from marriage or divorce.
Children's rights are an important example. Parents cannot use a private agreement to remove statutory protections relating to custody, maintenance or welfare. If a dispute arises, the court retains the responsibility to consider the children's best interests, irrespective of what their parents may have agreed before marriage.
Similarly, provisions that conflict with mandatory legislation, applicable Islamic Sharia principles or UAE public policy may be rejected. The fact that both parties voluntarily signed a document does not, by itself, make every clause legally binding.
This is why the drafting process matters as much as the decision to enter into an agreement. Financial arrangements should be clearly expressed, consistent with the governing legal framework and limited to matters that the parties are legally entitled to regulate between themselves.
A poorly drafted agreement may create a false sense of security. What appears to be comprehensive protection may prove ineffective when a court is required to examine the document.
Financial Planning Should Begin Before Marriage
For couples with different nationalities, international investments, property portfolios or business interests, a prenuptial agreement can be a useful instrument of financial planning. It can help distinguish individual assets from jointly acquired interests, clarify responsibilities and reduce the scope for disagreements if the relationship ends.
However, its effectiveness depends on choosing the appropriate legal framework from the beginning. Couples should establish which personal status regime will govern their marriage and whether the proposed financial arrangements need to be incorporated into an authenticated marriage contract or submitted through a recognised civil marriage procedure.
Those who already have agreements signed abroad should not assume that relocation to the UAE leaves their legal position unchanged. A review of the document against UAE legislation, the applicable foreign law and any relevant nationality considerations can help identify potential weaknesses before a dispute arises.
It is equally important to revisit the arrangements when circumstances change. A new nationality, relocation, acquisition of substantial property, expansion of a business or significant change in financial responsibilities may justify a fresh legal assessment.
Marriage is entered into with the expectation of a shared future, but financial circumstances and personal priorities can evolve over time. Preparing an agreement does not mean anticipating the end of a relationship. Rather, it provides an opportunity for both partners to understand their respective rights and responsibilities and make informed decisions while their relationship is on stable ground.
There is one additional qualification worth retaining when interpreting the new conflict-of-laws provisions. Article 22 states that the preceding conflict-of-laws rules do not apply where a special law or an international treaty in force in the UAE provides otherwise. This is another reason why the applicable personal status regime must be identified before reaching a conclusion about an overseas agreement.
Dr Sunil Ambalavelil is the Global Executive Chairman of Kaden Boriss, an international law firm specialising in franchise and business agreements. A seasoned legal adviser, he has advised and supported the international growth of numerous global brands, helping them navigate the legal complexities of cross-border expansion.
For enquiries or further information, contact ask@tlr.ae or call +971 52 644 3004. Follow The Law Reporters on WhatsApp Channels.